
Audio By Carbonatix
The Government of Ghana would require between US$600.0 million and US$800.0 million for external debt service in 2024.
Out of this, an estimated US$477.0 million would be used for Eurobond debt service.
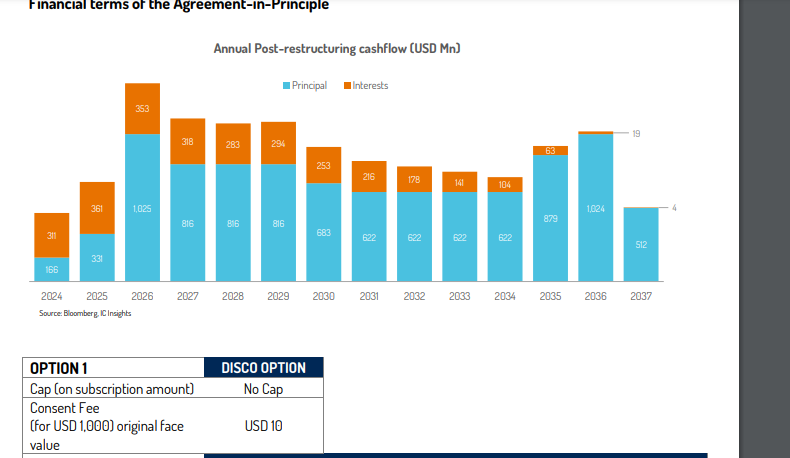
According to IC Africa Research, the estimated cash flow on the restructured Eurobonds envisages the resumption of debt service on the restructured Eurobonds from July 2024.
“Accounting for the ongoing multilateral debt service (given that these debts were outside the perimeter of debt restructuring), we think the authorities would require between US$600.0 million – US$800.0 million for external debt service in 2024. These estimates exclude the US$1.6 billionn legacy arrears owed to the Independent Power Producers, out of which only US$400.0 million has been paid, and other commercial creditors”.
“Extending the outlook, the cash flow forecast shows intensified debt service obligation from 2026 – 2030, from peak US$1.4bn to US$1.1 billion on the Eurobonds alone”, it added.
However, Ghana’s forex reserves (excluding oil funds and encumbered assets) stood at US$4.3 billion in April 2024 (2.0 months of import).
This, IC Africa Research said emphasises its longstanding view that the government have been in reserves accumulation mode in anticipation of external debt service resumption rather than sufficient foreign exchange market support.
Consequently, it stressed that it remained less bullish on the outlook for the Ghanaian cedi as it sees limited sources of sizable foreign exchange (FX) inflow to the market.
Limited upside risks for secondary market pricing
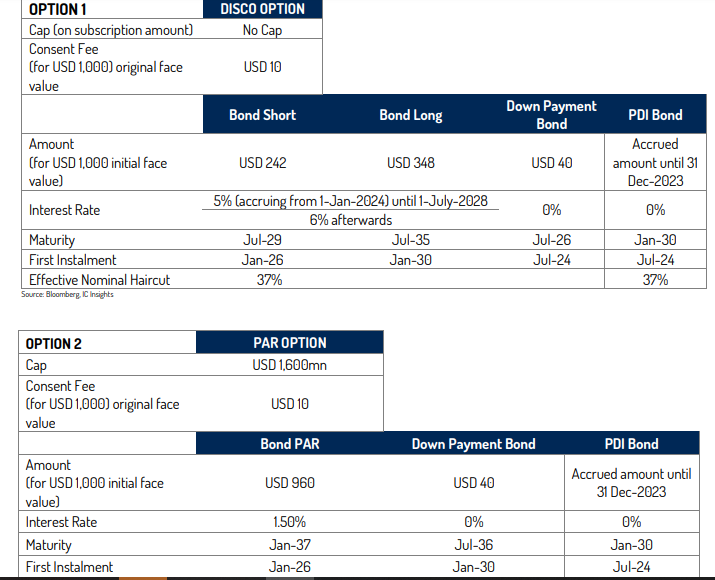
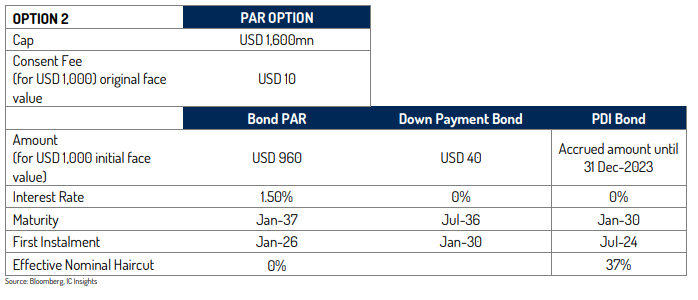
Following the significant move in restructuring the Eurobonds, IC Africa Research added that it envisages limited upside for secondary market pricing due to the deeper haircut and slashed coupon.
“Following our early May 2024 update note on the initial proposal in which we anticipated upside of between 10.0% and 20.0%, Ghanaian Eurobonds have posted an average price gain of 3.8% as of mid-day 24 June 2024. However, we opine that the new terms impose deeper losses on investors via the effective haircuts on principal and PDI, as well as the 50 basis points reduction in the stepped-up coupon rate (6.0%) while the lower coupon of 5.0% is extended for one extra year.”
“In view of this, we now see limited upside scope from the current average market cash price of US$53.4 per US$100.0 face value, with upside potential of between 5.0% – 7.0%.
Latest Stories
-
Police administration is doing a yeoman’s job – President Mahama
3 minutes -
GoldBod tells PAC Bank of Ghana authorised its foreign exchange transactions
3 minutes -
GCB customers call for more frequent engagement with bank leadership
7 minutes -
Dark Signals: The death trap of non-functioning traffic lights along Asokwa-Aputuogya Road
9 minutes -
80–90% of gold purchased and exported is now refined in Ghana– Sammy Gyamfi
27 minutes -
Dichemso M/A teachers go house-to-house to get absent pupils back to class after strike suspension
30 minutes -
Meet Dr Hazel and Nhyira: Mother and daughter called to the Ghana Bar
33 minutes -
Black Star Fashion Week: Can Ghana turn the runway into a tourism attraction?
34 minutes -
Ghana sends 61 health workers to Grenada under Labour Export Programme
46 minutes -
Central banks should avoid reacting too strongly to headline inflation – IMF
52 minutes -
Kumasi: One injured, shops destroyed in Atasemanso fire in Kumasi
1 hour -
Global economy proving resilient, growth projected at 3.1% in 2026 – IMF
1 hour -
NDC targets all 6 parliamentary seats in Ahafo Region for 2028
1 hour -
Ghana targets thousands of overseas nursing jobs under Labour Export Programme
1 hour -
Pius Hadzide explains why Sports Ministry always attracts scandals
1 hour