

Audio By Carbonatix
Small and medium-sized enterprises (SMEs) can now access loan facilities from credit institutions using movable assets as collateral under the new Borrowers and Lenders Act 2020.
For years now, traditional banks have maintained a rigid fixation on land title and brick-and-mortar buildings as the sole keys for businesses to access credit.
This rigid collateral requirement by the lenders hindered local businesses from actively accessing loans to support business growth.
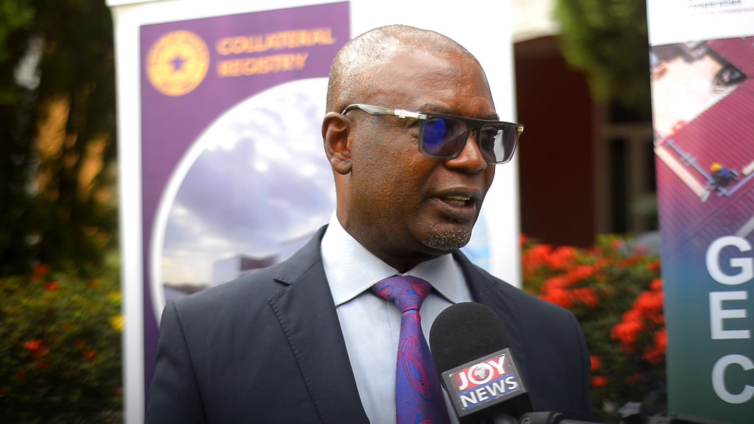
Assistant Director at the Collateral Registry Department of the Bank of Ghana, Alexander Koomson, said the introduction of movable assets into the collateral framework was intended to broaden the range of assets businesses could use to secure financing.
“We looked at how best we could help these enterprises and businesses obtain loans from the bank in the absence of immovable assets hence, we introduced movable assets as an option,” he said.
Speaking during a sensitization workshop on the Lenders and Borrowers Act 2020 in Kumasi, Mr. Koomson explained such assets could include vehicles and other movable property, in addition to immovable assets traditionally used as security.
He explained that the Collateral Registry was established under the framework governing lender-borrower relationships, with a key focus on security transactions.
Mr Koomson also stressed the importance of registration, saying lenders can only fully benefit from the protections available under the system when security interests are properly registered with the Collateral Registry.
He further disclosed that steps were being taken through the regulatory framework to facilitate the registration of financial technology companies, making participation in the Collateral Registry system a requirement for relevant institutions.
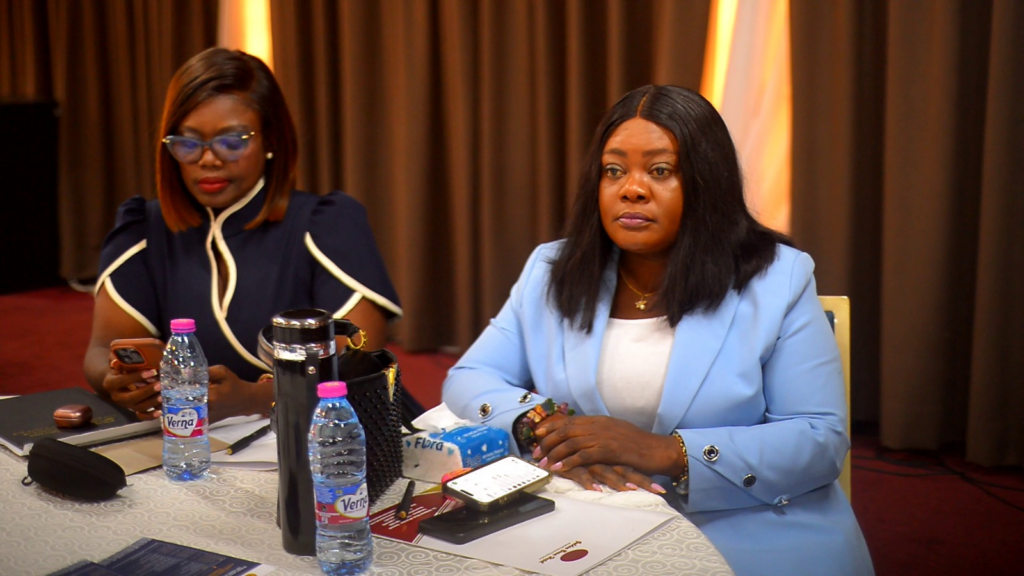
The two-day regional sensitisation programme organised by the Bank of Ghana sought to educate businesses and other stakeholders on the legal framework governing lending and borrowing and the use of collateral in accessing credit, highlighting their rights and responsibilities under the new Act.
The event also focused on expanding access to credit through collateral and strengthening the relationship between financial institutions and businesses.
Chairperson of the Agribusiness Sector at the Association of Ghana Industries (AGI), William Agyei-Manu, said businesses continue to face significant difficulties in securing financing despite recent reductions in key interest rate benchmarks.
According to him, setting up and running a business in Ghana remains challenging, with access to finance being one of the major hurdles confronting private-sector operators.
He therefore appealed to the Bank of Ghana to consider a moratorium or other supportive measures relating to the acquisition of finance, arguing that businesses need sufficient room to access and utilize credit to expand their operations.
“Setting up Agri businesses is quite difficult, so we as AGI have called for a moratorium on these finances to help,” he said
Regional Chairman of the Ghana National Chamber of Commerce and Industry (GNCCI), Kumasi Branch, Edward Yaw Afriyie, noted that increased awareness of the Borrowers and Lenders Act and the Collateral Registry could make it easier for businesses to engage banks when seeking loans.
He said the timing of the programme was particularly relevant given the reduction in the Monetary Policy Rate and the Ghana Reference Rate, which he said had contributed to lower lending rates.
“Cheaper credit ought to mean more working capital, more expansion, more jobs,” he said, while acknowledging that the reduction in benchmark rates does not automatically resolve the challenges businesses face in securing loans.
Mr. Afriyie said there remained a significant gap between changes in headline interest rates and the practical experience of businesses seeking financing.
The two-day programme brought together representatives of the Bank of Ghana, business associations, financial institutions and businesses to discuss the Borrowers and Lenders Act, 2020 and the operations of the Collateral Registry.
Latest Stories
-
Baffour Awuah cooperating with investigators after surrender and arrest – EOCO
1 minute -
Destruction of aspirants’ posters breaches democracy—Ashanti NPP Communications Director
11 minutes -
BNI investigates Ampofo Ankrah over alleged $623,000 World Cup visa scheme
23 minutes -
NPP National Delegates Conference: Police announce road closures, diversions around Baba Yara Stadium
31 minutes -
Agric Committee demands financing plan for Pwalugu Irrigation Project before 2027 Budget
33 minutes -
Minority calls for the immediate suspension of Ghana-Colombia maritime agreement
44 minutes -
Ghanaian professional Sydney Hushie appointed UNFPA Chief of Digital Centre of Excellence
49 minutes -
GHS urges health managers to use community scorecards to improve healthcare delivery
56 minutes -
Ekyeamamfrom-Pivot irrigation project 90% complete but stalled over unpaid certificates
59 minutes -
When the Gavel speaks, where is the choir that once sang for Wontumi?
60 minutes -
NPP does not need a new chairman: It needs a brand architect
1 hour -
GNFS contains fire at Avenor North Industrial Area in Accra
1 hour -
NITA appoints Anthony Owusu-Ansah as Acting Deputy Director-General
1 hour -
RANA warns Salomey Bafoh case could have chilling effect on free expression
1 hour -
Who is the ‘hero’ Indian pilot who was stabbed on Israel-bound flight?
2 hours