

Audio By Carbonatix
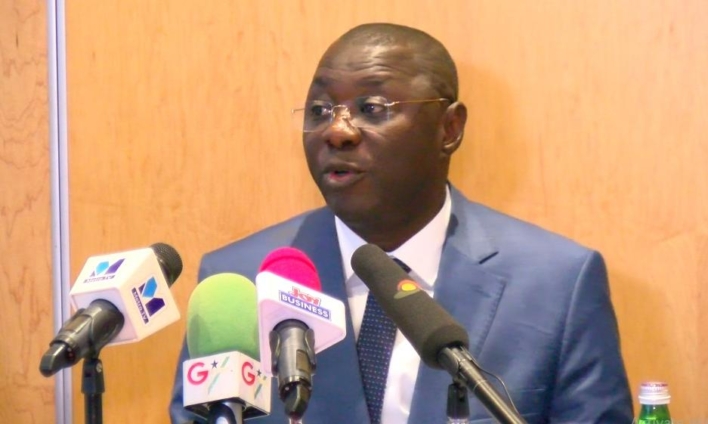
Finance Minister Dr Mohammed Amin Adam is confident that the government has outperformed the opposition National Democratic Congress (NDC) on economic metrics.
According to him, the performance of the New Patriotic Party (NPP) on the economy leaves nothing for the NDC to trumpet in their campaign ahead of the 2024 elections.
The Karaga legislator said this when he addressed attendees at a UK Town Hall meeting.
At the event, Dr Adam announced the completion of Ghana’s debt restructuring programme with its official creditors.
The Minister explained that government has successfully restructured its debt of 5.1 billion dollars with these creditors, in addition to concluding the restructuring of $13.1 billion with Eurobond holders.
On the back of this, he projected that the cedi will appreciate against the dollar adding that "watch the cedi to the dollar after tomorrow... Let's watch it and see, the confidence will come."
"The investors will return to Ghana and the growth trajectory will even become clearer for all of us."
He insisted that "this election is an election for us to win, NDC can no longer compete."
"On the economy, our record is better than their record. On the size of the economy, we've done better than them. On per capita income, we've done better than them. On job creation, we've done better than them. On economic growth, we've done better than them."
The government recently secured delayed payment on interest and postponement on the maturity date in a restructured debt deal with bilateral creditors.
To meet its IMF target, the $77 billion economy needs to reduce debt to 55% of gross domestic product by 2028, compared with a burden of 109% projected for the year before Ghana began restructuring.
The current bondholder agreement would leave debt slightly above that target.
Ghana’s economy fared better than the IMF expected, expanding 2.9% in 2023 compared to an initial IMF target of 1.5%. That means a revised DSA would accommodate the agreement with bondholders, Adam said.
Ghana began working to revamp its debt a little over a year ago as part of a deal with the International Monetary Fund, reaching an agreement in principle with bilateral creditors in January to rework $5.4 billion of obligations under the Group of 20 Common Framework for Debt Treatment.
Latest Stories
-
Interest payments to average a high 20% of government revenue over next 4 years
2 hours -
Strategy of accumulating foreign reserves, gold carries high fiscal cost – S&P Global
2 hours -
Weak institutional arrangements, high debt servicing constrain Ghana’s rating – S&P
2 hours -
Bond market: Turnover declined by 28% to GH¢1.56bn
3 hours -
Volta Region National Public Speaking contest advances drug prevention conversation
3 hours -
New health training facility at Ampoma-Jema to address admission shortfalls, but Minister flags missing amenities
3 hours -
Black Challenge unveiled with sights set on Amputee World Cup glory
3 hours -
Pay striking teachers before expressway spending, Dr Kingsley Agyemang tells government
4 hours -
Customs intercepts assault rifle, two pistols and 610 rounds of ammunition at Tema Port
4 hours -
PKO boxers secure wins at Odwira Festival
5 hours -
South Tongu Records Rise in Teenage Pregnancy
5 hours -
Cabinet threw out US health compact faster than anything I’ve seen – Mahama
5 hours -
MoFA urges Finance Ministry to reverse World Bank food programme withdrawal over GH¢643m commitments
5 hours -
NAGRAT demands signed timelines before calling off strike
5 hours -
National Investment Quiz: West Africa SHS, St. Louis SHS advance to semi-finals
6 hours