
Audio By Carbonatix
Since 2017, we have argued against the change of fiscal accounting by the current government in treating ‘exceptional’ expenditure items and arrears as a footnote.
In particular, it has used this approach to account for the banking and energy sector bailout costs.
In fact, in the case of the energy sector costs, it has even skipped the footnote treatment and brazenly added the expenses and arrears to amortisation.
This is a departure from what past governments have done. They treated all exceptional revenue inflows and expenditure outflows ‘above the line’; hence they have added them to revenue, expenses or arrears, but showed them distinctly in the fiscal framework.
This means that the exceptional revenues decrease the deficit while the counterpart expenditures increase the budget deficit (also called the fiscal balance). Examples include divestiture and HIPC/MDRI (as revenues or receipts) and single spine, excessive subsidy, additional fuel cost for thermal plants during droughts, or gas supply disruption (as expenses).
However, when it came to the exceptional bailout costs, this government excluded the cost and boasted of better budget deficit performance. Note that at the same time government treated the related ESLA flows as revenues, which minimises the deficit or fiscal balance.
It is disappointing to note the defence from well-informed experts and institutions that govermment had the option to go against well-known GFS and IPSAS accounting rules on the matter.
The practice also defies the accrual accounting rules in the PFMA – and other well-informed experts simply chose to remain silent, including those who should set our national standards.
We must state that the IMF and rating agencies now isolate but include exceptional expenditures in determining the budget deficits or fiscal balance. To date, however, government has not changed this practice. Of course, the ballooning public debt stock has exposed this practice as a hoax.
As we wait for the budget for 2022 and the Provisional outrun for 2021, we wait to see how government will treat the ‘exceptional’ IMF US$1billion SDR inflows or revenues as a Budget Appendix Footnote or as income.
If it does, it will be following the ‘consistency’ rule but be incorrect. If it does not and follows what it does with ESLA now, it will also be consistent with their current practice but simply exercise discretion or an option that does not warrant it comparing its fiscal performance to those of any past governments.
It will continue to be disappointing for our experts and institutions to continue defending this practice or remaining silent.
****
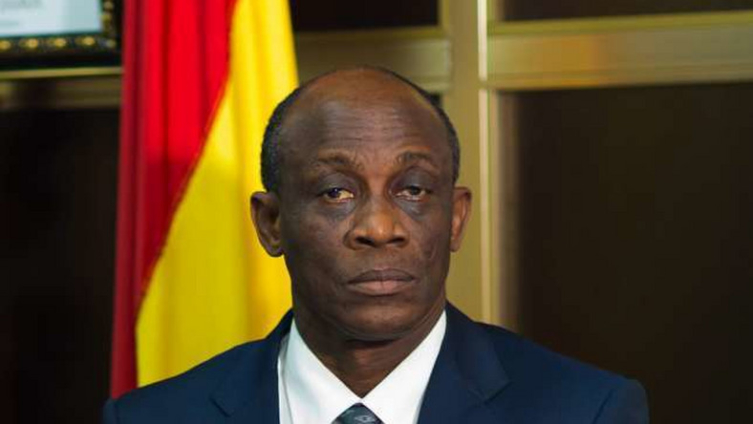
The writer is the former Finance Minister during the Mahama administration.
Latest Stories
-
Ghana housing finance conference adopts communiqué to improve affordable housing access
4 hours -
Special Initiatives Minister urges Wa Technical Institute to enrol more girls as EU-backed solar training lab opens
4 hours -
In the matter of my first year at the Bar
4 hours -
ActionAid Ghana calls for an end to child marriage, greater investment in girls’ rights
4 hours -
Newsfile to tackle World Cup visa scandal, beach demolitions, education strikes, BRICS bid
5 hours -
UK-Ghana Trade & Investment Summit: Trade Resource Centre to help businesses maximise UK-Ghana trade opportunities
5 hours -
Embassy of Denmark celebrates World Maritime Day
5 hours -
Linking LEAP to productive inclusion could cut extreme poverty by 2030 – UNICEF
6 hours -
Trade Ministry backs use of creative arts to rehabilitate prison inmates
6 hours -
Negotiations with government to continue despite strike suspension – GNAT
6 hours -
‘Ghana cannot afford to waste public resources; every cedi has a job’ – Ato Forson
6 hours -
Ghana expects economic boost as World Assemblies of God Congress brings 10,000 delegates to Accra
7 hours -
Joy in Nayilifong as Farouk Aliu Mahama donates 100kVA transformer to improve power supply
7 hours -
Chief Justice urges employers to tackle mental health stigma in workplaces
8 hours -
Analysis: Ghana’s yellow fever numbers reveal a gap between vaccination and protection
8 hours