
Audio By Carbonatix
Crisis-hit Pakistan has reached a staff-level agreement with the International Monetary Fund (IMF) over $3bn (£2.4bn) of funding.
The deal, which still needs to be approved by the global lender's board, comes after an eight-month delay.
The South Asian nation is facing its worst economic crisis since independence from Britain in 1947.
To help secure the deal, Pakistan's central bank raised its main interest rate to a record high of 22% on Monday.
Pakistan's economy, which was already struggling after years of financial mismanagement, has been pushed to the brink by a global energy crisis and devastating floods that hit the country last year.
"The economy has faced several external shocks such as the catastrophic floods in 2022 that impacted the lives of millions of Pakistanis and an international commodity price spike in the wake of Russia's war in Ukraine," Nathan Porter, IMF's mission chief for Pakistan said.
"As a result of these shocks as well as some policy missteps... economic growth has stalled," he added.
Once agreed at staff level such deals are usually granted by the IMF's Executive Board. The board is expected to consider the agreement in the coming weeks.
"This deal gives Pakistan the economic breathing room that it so badly needs," Michael Kugelman from the US-based Wilson Center think tank told the BBC.
"The question is if it can use this IMF deal as an opportunity to pivot from immediate relief to a long-term recovery," he added.

Katrina Ell, a senior economist at Moody's Analytics, said: "High inflation coupled with limited foreign reserves and lacking macroeconomic stability take time and sustained fiscal discipline to overcome."
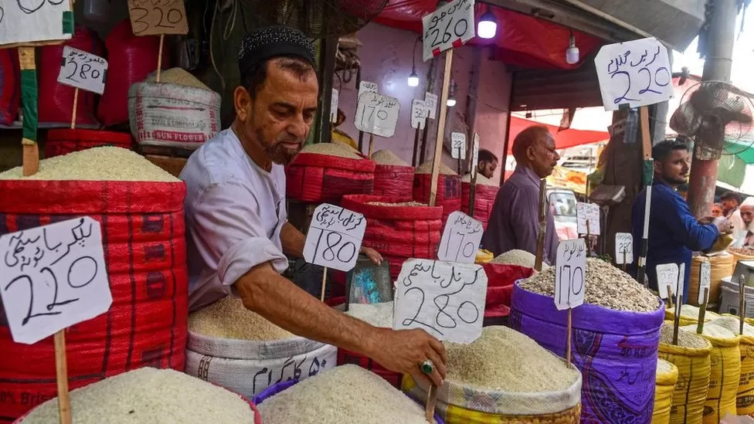
Pakistan's annual inflation rate hit a fresh record high in May of almost 38%.
The $3bn of funding, which will be spread over nine months, is higher than expected.
Pakistan was awaiting the release of the remaining $2.5bn from a $6.5bn bailout package agreed in 2019, which expired on Friday.
The nation of more than 230 million people has been struggling for years to stabilise its economy.
This year the country's foreign exchange reserves fell to a level that covered less than three weeks of imports.
Deadly clashes between supporters of Pakistan's former prime minister Imran Khan and police have also rattled financial markets.
In May, Mr Khan was arrested on corruption charges, in a move that has since been ruled as illegal by the country's Supreme Court.
Over the last year the Pakistan rupee has fallen by around 40% against the US dollar.
Separately, donors from around the world have pledged more than $9bn to help Pakistan recover from devastating floods that hit the country in 2022.
It had been estimated that it needed more than $16bn to recover from the disaster.
Latest Stories
-
Ghana needs a law to sustain constitutional reforms – CDD-Ghana
27 minutes -
COVID fumigation audit: Auditor-General has a lot of questions to answer – Akwatia MP
27 minutes -
Stranded Ghanaian medical graduates in Cuba appeal to Mahama for immediate return
35 minutes -
GNFS contains fire outbreak at Teshie Lekma Road near Lekma Hospital
7 hours -
Samia Nkrumah rejects the narrative that Ghanaians were happy after Nkrumah’s overthrow
8 hours -
A Mother’s pain: Tribute by Ivan Baidoo’s mother
8 hours -
‘Forgive us for staying away’ — Samia Nkrumah leads family back to Nkroful, pledges to preserve Nkrumah’s legacy
8 hours -
Ernest Nuamah scores twice as Lyon beat Rennes
8 hours -
‘My dear Ivan’ – A father’s tribute to a son tragically killed
8 hours -
GNPC Explorco advances Voltaian Basin drilling preparations with 13.5km access road
9 hours -
Cabinet approves facility manager for Borteyman Sports Complex – Kofi Adams
9 hours -
Sanitation is improving; critics may be ‘living in another world’ – Salaga South MP replies Bekwai MP
10 hours -
Government must do more to tackle sanitation crisis – Bekwai MP
10 hours -
World Cleanup Day: GFF begins sanitation education in local communities
10 hours -
EU Ambassador, IGP discuss stronger cooperation on policing and security
10 hours