
Audio By Carbonatix
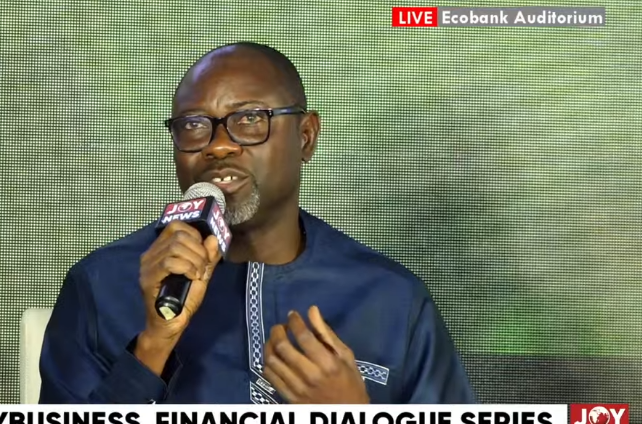
The Chief Operating Officer of the Ghana Incentive-based Risk-sharing System for Agricultural Lending (GIRSAL), Samuel Yeboah, says production challenges, market volatility and inadequate business records remain major obstacles to financing Ghana’s agricultural sector.
He said while banks are often criticised for considering agriculture too risky to finance, the sector faces genuine risks that can undermine farmers’ production, earnings and ability to repay loans.
Speaking at the Ecobank-JoyBusiness Financial Dialogue Series on Tuesday, September 22, Mr Yeboah said agricultural lending required a clear understanding of the risks involved and the circumstances of the businesses seeking financing.
“The perceived risk the banks talk about is real. No farmer or no practitioner will say that agric has not got any inherent risk,” he said.
Production and market uncertainties
Mr Yeboah explained that agricultural production was particularly vulnerable to factors beyond farmers’ control, including inadequate rainfall, crop diseases and crop failure.
“Today you plant, tomorrow the story is there’s no rain, and there’s failure, disease and all,” he said, highlighting how such uncertainties could affect farmers’ output and their ability to repay loans.
He also identified market volatility and unpredictable commodity prices as significant risks confronting farmers and agribusinesses.
According to him, farmers often make production decisions based on expected market conditions, only to encounter unfavourable prices or difficulties selling their produce at harvest.
“You plant today expecting to sell your commodity at a certain price. For one or two reasons, there are heavy imports into the country, and you cannot sell,” he said.
He explained that an influx of imports or other market disruptions could leave farmers struggling to sell their produce, affecting their cash flow and ability to service loans.
Mr Yeboah cited instances where harvested commodities had remained unsold for extended periods, describing such situations as genuine risks that financial institutions must consider when assessing agricultural loan applications.
“These are real risks,” he stressed.
Poor record-keeping complicates loan assessments
Beyond production and market risks, Mr Yeboah identified inadequate business records as another major constraint to agricultural financing.
He said many agribusinesses, particularly smallholder farms, failed to maintain proper records of their operations, making it difficult for banks to assess their financial performance and creditworthiness.
“There’s this information asymmetry where banks are not able to really understand the operation of the agribusinesses, because the agribusinesses do not keep good records,” he said.
He explained that farmers needed to document key aspects of their operations, including production volumes, sales, yields and revenue over several production cycles.
A rice farmer, for instance, should be able to provide records showing annual production volumes, sales and yields to help lenders assess the performance and financial viability of the business.
“Has he documented his volumes that he attained? How much has he sold? What are the yield levels?” he asked.
Mr Yeboah said such records would enable financial institutions to analyse business trends and make more informed lending decisions.
GIRSAL stresses due diligence
Mr Yeboah said understanding the operations of agribusinesses was essential to structuring financing that reflected the realities of the agricultural sector.
He said GIRSAL conducts due diligence on businesses to help financial institutions understand their operations and assess their financing needs.
“At GIRSAL, we do a lot of due diligence to actually understand the business before we can help the financial institutions to structure the business,” he said.
He added that lenders needed to understand farmers’ production cycles, harvesting periods and post-harvest decisions, including how they manage or sell their produce.
“Some harvest and they keep their produce because they want to speculate. All these things must be known,” he said.
According to him, without adequate documentation and information about these activities, financial institutions may struggle to properly assess an agribusiness and determine its capacity to repay a loan.
“But if the business is not able to document all these things, to give that adequate information to the financial institution, the financial institution will not be able to understand the business properly,” he said.
Latest Stories
-
Kwame Nkrumah’s legacy must remind public officials that authority is a trust — Julius Debrah
2 minutes -
Mr Joseph Benjamin Eyison Jnr aka Kojo Kum Panyin
4 minutes -
Hollard Ghana mourns Group CEO Patience Akyianu
5 minutes -
High cost of domestic airline fares: can the government do something about it?
14 minutes -
Fire brought under control near Osu Castle
16 minutes -
Eleven injured in shooting outside Turkish school
18 minutes -
Ten years after the blackouts, what changed in Ghana’s power story?
25 minutes -
Fisheries Commission inaugurates national-level fisheries co-management committees with support from GFRA
35 minutes -
Rafatu Inusah appointed Chef de Mission for 2027 Commonwealth Youth Games
37 minutes -
Production, market risks and poor records constrain agricultural lending – GIRSAL
41 minutes -
Photos: Gender Ministry presents 2027–2030 priorities at budget technical hearing
51 minutes -
Photos: Mahama engages global leaders in Presidential Roundtable in New York
52 minutes -
Ecobank deepens support for agriculture with dedicated expertise and training – Charlotte Amanquah
57 minutes -
High collateral, documentation requirements limiting farmers’ access to finance – PFA
1 hour -
NPP will be out of opposition in just two years – Afoko vows
1 hour